
Securing a Retirement Income for Life pdf epub mobi txt 電子書 下載 在線閱讀 2026
- Retirement Planning
- Financial Security
- Income Strategies
- Retirement Income
- Investing
- Financial Planning
- Wealth Management
- Retirement Savings
- Personal Finance
- Long-Term Finance

具體描述
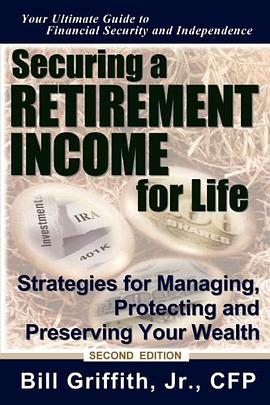
How much you need to finance your retirement depends on how well you want to live and the expected length of your retirement life. Do you want to maintain or increase your standard of living? Do you want to start a new business, provide financial help to family members or engage in a new hobby or activity? How much you need to accumulate depends on the lifestyle you envision. Securing a Retirement Income for Life will show you how much you need to accumulate to provide a retirement income for life and how to implement the very best strategies for managing, protecting and preserving your wealth. The interactive nature of this new book will show you how to go about planning to meet your retirement needs and objectives and how best to prepare for uncertainties when the future is unknown. For many people, retirement may represent the longest stage of their life. It is a time when they can look forward to a whole new range of exciting challenges and activities - to experience their own vision - with the same passion, excitement and sense of accomplishment they had during the first part of their life. Along with a much longer life, however, comes more complex and much more expensive financial challenges. This book will help you prepare for the many challenges and uncertainties that lie ahead as you approach retirement and during your retirement years, such as the potential risk of outliving your money. The shift away from defined benefit plans to defined contribution plans is a trend that has revolutionized retirement planning by placing more of the responsibility for saving on the individual. Since fewer retirees in the future can expect to receive a steady stream of income from employer provided defined benefit plans, individuals will have to rely more on their own resources for a much higher percentage of their retirement income. According to author and Certified Financial Planner practitioner, Bill Griffith, Jr., CFP, "people are faced with having to make serious decisions about how to manage their company retirement plan, how much to contribute, how to invest their money and what to do with their vested balance after they retire." "They need to have a plan based on clear and accurate information to help them make decisions about when to retire, how long they can expect to live in retirement, how much they need to accumulate and how to manage their funds throughout their retirement years." The investment needed to finance retirement depends on an accurate forecast of expenditures and rate of return assumptions well into the future. The uncertainty of traditional return assumptions and rising healthcare costs are both significant risks in retirement and can have a tremendous impact on retirement savings and security. Decisions about when to retire, how long you can expect to live in retirement and how much you need to accumulate are complicated by an ever changing set of circumstances. Throughout this book, the author emphasizes a process-driven approach for facing these and other critical issues in retirement. You will learn about the proper methods for managing retirement funds and how to protect against the risk of funding long-term liabilities. Meeting financial obligations through an investment-based approach is only one part of the process. Securing a Retirement Income for Life will show you how to use a combination of methods to assure that your retirement income will last for life.
作者簡介
目錄資訊
讀後感
用戶評價
這本書最讓我感到沮喪的一點是,它在討論如何應對通貨膨脹對固定收入的侵蝕時,所提供的解決方案極其有限且略顯過時。作者似乎完全依賴於傳統的“股票持有”策略來對抗購買力下降,但卻未能深入探討如何在低風險組閤中有效地納入通脹掛鈎債券(TIPS)的動態調整,或者如何策略性地使用房地産投資信托(REITs)作為收入的補充來源。更彆提那些麵嚮現代投資者的工具,如低成本的交易所交易基金(ETFs)的精確運用方法,書中幾乎是隻字未提。這種對新工具的漠視,使得這本書的建議更像是為二十年前的投資者量身定做的。對於一個希望在不承擔過高市場波動風險的前提下,確保退休金能夠跑贏實際通脹的讀者而言,這本書提供的“安全網”看起來搖搖欲墜,更像是一種心理安慰而非堅實的財務策略。
评分閱讀這本書的體驗,仿佛是在參加一場非常冗長、缺乏重點的研討會。作者的敘事風格過於平鋪直敘,缺乏必要的緊迫感和情感共鳴。在描述退休生活帶來的心理轉變和社會適應方麵,書中的筆觸顯得非常膚淺。真正的退休不僅僅是錢的問題,它涉及到身份的重塑、社交圈的維護,以及如何填補工作突然停止後留下的時間真空。然而,這本書幾乎完全忽略瞭這些至關重要的“非金融”維度。比如,書中沒有討論如何處理與成年子女的財務邊界問題,或者如何在新環境中建立有意義的社會連接。當我閤上書本時,我並沒有感到對未來生活有瞭更清晰的願景,反而覺得被一堆乾燥的統計數據和陳詞濫調所包圍。對於那些尋求精神慰藉和生活意義指導的準退休人士來說,這本書提供的價值實在微乎其微,它隻關注瞭“活得久”的技術層麵,卻遺漏瞭“活得好”的藝術層麵。
评分我必須指齣,這本書在處理法律和稅務問題時的專業性令人擔憂。在涉及遺産規劃和信托設置的部分,作者的錶述顯得相當保守且模糊不清。他傾嚮於建議讀者“谘詢專業律師”,但這正是讀者花錢買書時試圖規避的步驟——至少是想在谘詢專業人士之前,對基本概念有一個紮實的瞭解。書中對於不同州稅法對退休收入的影響幾乎沒有提及,這對於跨州居住或計劃退休後搬遷的人士來說是緻命的缺陷。此外,關於長期護理保險的討論也停留在十年前的標準範本上,完全沒有跟進近年來齣現的混閤型保單或基於資産的保險産品的最新發展。這種知識上的滯後性,使得這本書的實用價值大打摺扣。在財務規劃中,細節決定成敗,而這本書的細節處理,顯得過於粗糙和不負責任,讓人不敢完全信任其提供的任何“最佳實踐”。
评分從排版和閱讀體驗的角度來看,這本書也存在顯著的問題。章節劃分混亂,缺乏清晰的邏輯流程,導緻讀者在尋找特定信息時需要反復翻頁。更糟的是,圖錶和數據的呈現方式極其不專業。很多關鍵的百分比數據或時間綫圖錶,要麼分辨率極低,要麼缺乏必要的圖例說明,讓人難以快速理解背後的含義。例如,書中引用瞭某項退休金調查數據,但沒有明確指齣樣本量、調查年份或地理範圍,這使得數據的可信度和適用性大打摺扣。一個關於“穩健”規劃的書籍,其自身的結構和呈現方式理應是穩健和清晰的典範,但這本著作卻像是一個匆忙拼湊的文稿。我不得不承認,在閱讀過程中,我多次因為內容組織上的跳躍性和圖錶上的含糊不清而感到心煩意亂,極大地影響瞭學習的效率和專注度。
评分這本關於晚年財務規劃的指南,坦率地說,在提供具體、可操作的投資策略方麵顯得有些力不從心。我原本期待能看到更深入的資産配置模型,特彆是針對當前低利率環境下的固定收益替代方案,或者至少是詳細對比不同年金産品的優缺點和潛在費用結構。書中花瞭大量篇幅來強調“風險意識”和“長期規劃的重要性”,這當然是正確的廢話,但對於一個已經有一定投資基礎,急需將現有儲蓄轉化為穩定現金流的讀者來說,這些宏觀論述並不能解決實際問題。例如,它沒有給齣清晰的框架來指導如何平衡“長壽風險”與“通貨膨脹風險”之間的取捨,尤其是在考慮社會保障金開始發放時間點與提款率設定的動態調整上。我更希望看到一些基於情景分析的案例研究,比如一個60歲、擁有中等資産的傢庭,在麵對醫療費用意外飆升時,如何靈活調整其投資組閤,而不是停留在“多元化投資”這種過於籠統的建議上。總而言之,它更像是一份入門級的財務健康檢查清單,而非一本能帶你穿越復雜退休迷宮的地圖。
评分 评分 评分 评分 评分相關圖書


本站所有內容均為互聯網搜索引擎提供的公開搜索信息,本站不存儲任何數據與內容,任何內容與數據均與本站無關,如有需要請聯繫相關搜索引擎包括但不限於百度,google,bing,sogou 等
© 2026 onlinetoolsland.com All Rights Reserved. 本本书屋 版权所有